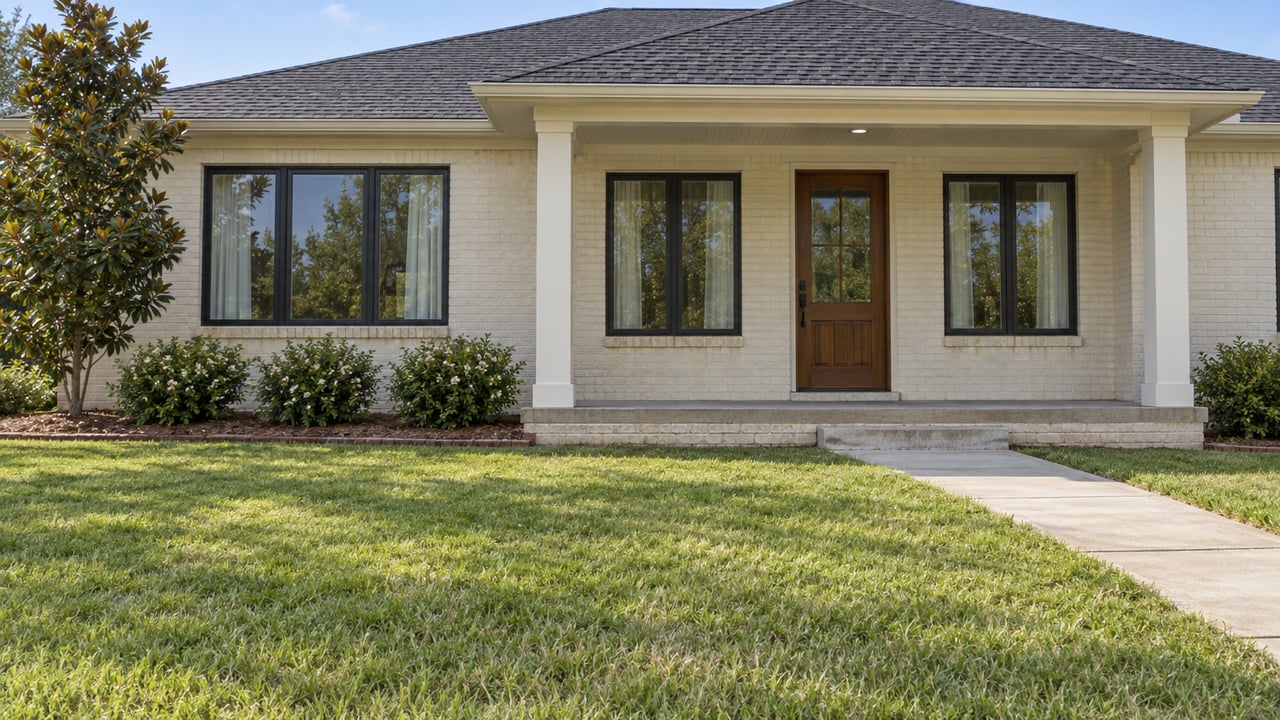
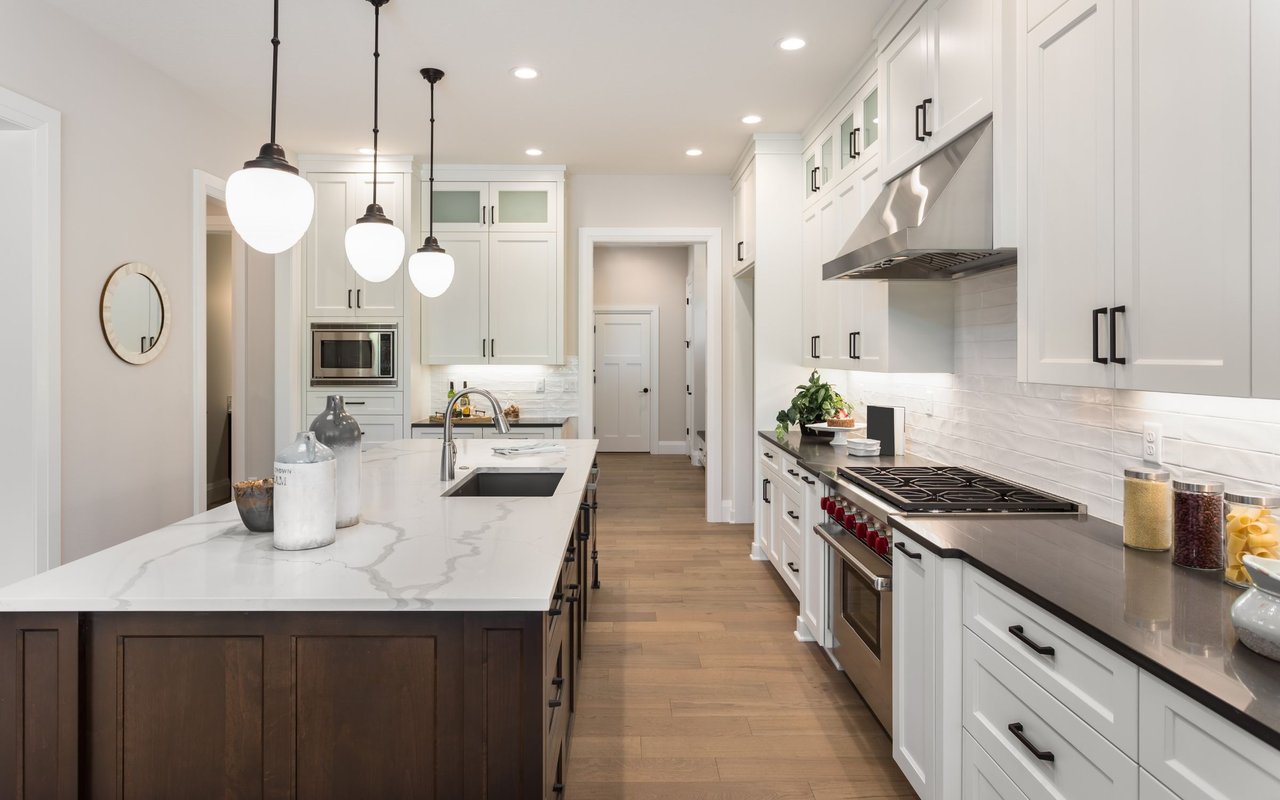
104 Harbourside Drive in The Grove at Sugar Mill Pond is a move-in-ready 3-bedroom, 2-bath Manuel Builders home of 1,380 square feet. It has 10-foot ceilings, a tray ceiling with wood beams in the living room, and a ventless gas fireplace. The asking price is $319,900. Above the price, the listing offers "up to $12,465 in closing costs or rate buydown."
If that home closes at $319,900 with the full credit, the sale record will show $319,900. The $12,465 doesn't show up as a lower price, because it never was one. Right now in Youngsville, a good share of the price competition happens in that gap. The published medians are built from sale prices, so they make the market look firmer for sellers than it feels to a buyer holding a builder's incentive sheet.
The Number the Median Leaves Out
The REALTOR® Association of Acadiana publishes a monthly report for its whole market area. For August 2026, it lists a median sales price of $235,000, 70 days on market, 4.7 months of supply, and 97.5% of list price received. Under the table is this footnote:
Does not account for seller concessions and/or down payment assistance.
That line matters more in Youngsville than almost anywhere else in Acadiana, because so much of what's for sale there is new construction. A resale seller who wants to move a house usually cuts the price, and the cut shows up in the data. A builder can leave the price alone and fund closing costs or a lower interest rate instead. Two homes can cost their buyers about the same and still go into the record roughly $12,000 apart.
A September 29, 2026 explainer for appraisers from McKissock Learning cites the September NAHB/Wells Fargo survey. Nationally, 66% of builders were using sales incentives, and 38% were cutting prices. Those are national figures, not Youngsville rates. Still, the gap between them describes the habit. More builders reach for an incentive than for a lower price.
Reading July From the Contract Side
The latest Youngsville-specific numbers come from BY Local News' July 2026 market report, which draws on the ROAM MLS market summary. It was published September 4, 2026.
| July 2026, Youngsville | Figure | Change from July 2025 |
|---|---|---|
| Homes sold | 78 | +25.8% |
| Median sale price | $304,750 | +4.53% |
| Average sale price | $380,099 | +7.59% |
| Homes listed | 282 | +19% |
| Under contract | 67 | −1.5% |
| Average days on market | 84 | −6.67% |
| Absorption rate | 4.90 | +12.39% |
The column read July as brisk, with conditions favorable to sellers at most price points. The top three rows back that up. The bottom rows describe the next few months.
A closed sale records a contract signed weeks or months earlier, so the 25.8% jump in July closings mostly shows what buyers decided in late spring. The under-contract count is the closest thing in the report to what buyers were doing in July itself. That count slipped 1.5% while homes listed rose 19%. The absorption rate rose 12.39%. The report doesn't say whether that figure is in months. Either way, it moved in the same direction as listings.
The days-on-market figures point the same way. Median days on market was 39, and the average was 84. When the average runs more than twice the median, a typical home is selling quickly while a group of slower listings sits long enough to drag the average up. A builder holding finished inventory has every reason not to join that slow group, and a closing credit is how builders avoid it without changing the price on the sign.
I couldn't find a Youngsville report for August or September. Two caveats follow. July is the newest Youngsville snapshot available, and one month is a short read. The association-wide August table does show pending sales down 1.9% year over year and new listings down 13.6%, but that covers all of Acadiana, not Youngsville.
Four October Offers, Four Different Sets of Strings
This is what builders with homes in and around Youngsville were advertising in early October 2026. These come from live builder pages without publish dates, so confirm the terms on any specific home before you rely on them.
| Builder and community | Offer | Example home and price | Conditions |
|---|---|---|---|
| Manuel Builders, The Grove at Sugar Mill Pond, Youngsville | Up to $12,465 toward closing costs or a rate buydown | 104 Harbourside Dr, $319,900; 204 Harbourside Dr, $300,500 | Advertised on move-in-ready homes |
| Level Homes, Benson Grove, Canehaven and Sugar Mill Pond, Youngsville | Up to $14,000 toward a rate buydown, closing costs or cash at closing | 306 High Point Way, $291,429; 305 Sweet Harvest Rd, $382,135; 505 Oceans Blvd, $481,725 | Select inventory only; contract October 1 to 30, 2026; close by December 30, 2026; LH Lending financing or cash |
| DSLD Homes, Hidden Haven and Acadian Meadows, Lafayette | 4.99% initial rate with a 2/1 buydown on FHA, RD and VA loans; up to $12,000 toward buydown or closing costs; free blinds | 112 Oak Haven Dr, $251,980; 206 Hidden Meadows Dr, $249,632 | Contract October 1 to 31, 2026; close by December 31, 2026 |
| D.R. Horton, Cypress Falls, Broussard | $10,000 price reduction | 112 Harvest Falls Dr, $282,500 reduced to $272,500 | Community marketed to the Broussard and Youngsville area |
The D.R. Horton row is the only one where the discount shows up in the sale price. A $10,000 reduction on a Cypress Falls home will reach the comps. A $12,465 credit at Sugar Mill Pond won't. To a buyer, both are real money. In the public record, only one of them happened.
The conditions column is where these offers really differ. Level's credit requires financing through its affiliated lender or paying cash. It also applies only to "select inventory," and the listing pages don't say which addresses qualify. A buyer who already has a better quote from another lender has to weigh that quote against the $14,000. The October deadlines also add calendar pressure. A contract signed after October 30 or 31 falls outside both the Level and DSLD offers as written. DSLD's offer also shows two slightly different APRs on its main promotion page and its community cards, 7.93% and 7.98%. That's worth settling with the lender before you count on a payment.
Pricing a Credit the Way an Appraiser Would
The McKissock explainer warns appraisers not to treat a contract with a large seller-paid rate buydown the same as a sale with no concessions. It also says an advertised builder incentive doesn't automatically justify a dollar-for-dollar adjustment. The same piece notes that a subdivision where builders are aggressively buying down rates can behave differently from the resale neighborhoods nearby. A buyer can use the same reasoning to look at a Youngsville new build:
- Work out the effective price. At 104 Harbourside, $319,900 minus the full $12,465 comes to $307,435, if the whole credit goes to closing costs. Per square foot, that moves the home from about $232 to about $223. The 1,380 square feet don't change, so the credit is the only part of that math you can negotiate.
- Decide where the credit goes. Money spent on a rate buydown lowers the monthly payment. It doesn't lower the amount financed. A 2/1 buydown like DSLD's is temporary by design, and the rate steps up after the early years. How that compares to a permanent price cut depends on how long you plan to keep the loan. That's a question for your lender. It isn't something to settle from an incentive sheet.
- Price the strings. A required lender, a "select inventory" limit, or a closing deadline all cost something. Get the competing loan quote in writing before you decide whether the builder's offer comes out ahead.
- Compare against the price cut down the road. The Cypress Falls reduction and the Sugar Mill Pond credit are close enough in dollars that the right choice comes down to fit, floor plan, and location. The headline number doesn't settle it.
With my interior-architecture background, I'd add that the floor plan deserves more of your attention than the incentive. A credit runs out at closing. A plan that wastes 150 square feet on hallway is still there twenty years later.
What This Means If You're Selling a Resale Home Nearby
If you own an existing home in Youngsville, your buyers are probably looking at these builder pages too. When they compare your list price with a new build at a similar sticker price, the new build may effectively cost $12,000 to $14,000 less once closing is counted. That gap doesn't appear in the comps your agent pulls. July's 19% rise in homes listed, against a dip in homes under contract, means more homes are competing for each buyer.
Matching a builder dollar for dollar isn't the only response. Offering a seller credit toward closing costs puts you on the same terms the builder is using. Pricing slightly below the new-build sticker gets you noticed by buyers searching by price. What a resale home can offer that a spec home can't is a mature yard, a finished neighborhood, and no punch list. Those are worth pointing out in the listing.
Quick Questions
Is the Youngsville median price wrong? No. The $304,750 July 2026 median reflects recorded sale prices. It just doesn't tell you what buyers paid after builder credits. For its own August figures, the REALTOR® Association of Acadiana states plainly that its median doesn't account for seller concessions.
Do these incentives apply to every new home in Youngsville? No. Level limits its offer to select inventory. Manuel advertises its credit on move-in-ready homes. The DSLD promotion is listed for its Lafayette communities, Hidden Haven and Acadian Meadows, not for Youngsville. Confirm the offer on each specific address.
Why not just ask a builder for a price cut instead? You can ask. The public offers lean heavily toward credits. In this research, the clear price reduction was at D.R. Horton's Cypress Falls in Broussard. Which one is worth more depends on your loan terms and how long you expect to stay.
If you're comparing a Sugar Mill Pond spec home with a resale on the other side of Youngsville, or trying to decide whether a $14,000 credit with a required lender beats your own loan quote, I'm happy to lay the numbers side by side with you and walk through both floor plans before the October deadlines close. Let's Connect with Joan Beduze.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.